Debt Consolidation Advice in NJ: A Comprehensive Guide


Managing multiple debts can be overwhelming, especially if you're juggling various interest rates and due dates. For residents of New Jersey, debt consolidation might be a viable solution to streamline your financial obligations and potentially lower your monthly payments.
What is Debt Consolidation?
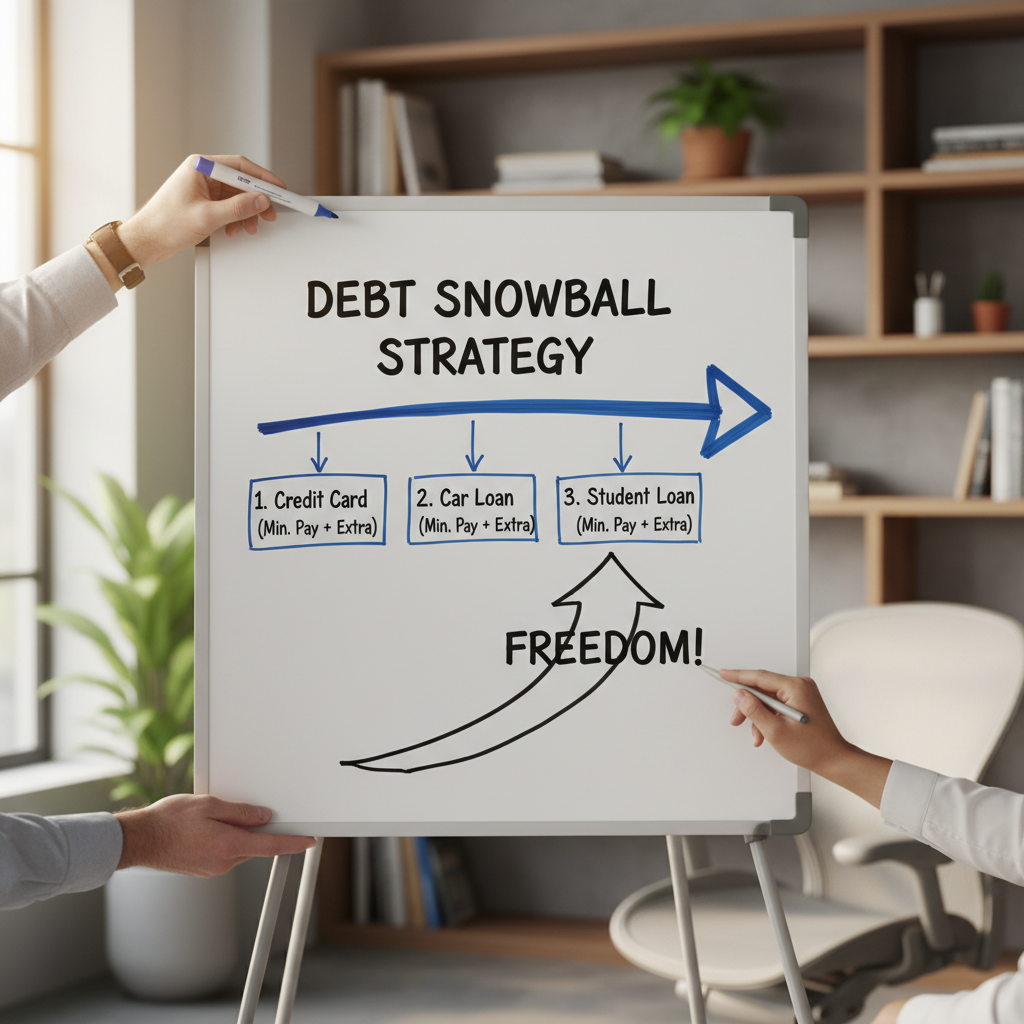
Debt consolidation is the process of combining multiple debts into a single loan or payment. This approach can simplify your finances by having just one monthly payment, often at a reduced interest rate. It's a popular strategy for those looking to manage credit card debt, personal loans, or other unsecured debts.
Benefits of Debt Consolidation
Consolidating your debts can offer several advantages:
- Lower Interest Rates: By consolidating, you may qualify for a loan with a lower interest rate, reducing the overall cost of your debt.
- Single Monthly Payment: Simplifies your financial management with one payment each month.
- Fixed Repayment Schedule: Helps you create a structured plan to pay off your debt.
Types of Debt Consolidation Loans
There are several types of debt consolidation loans available in New Jersey. Understanding your options can help you choose the best one for your situation:
Personal Loans
Personal loans from banks or credit unions can be used to consolidate debt. These loans often come with fixed interest rates and terms, making it easier to budget your payments.
Home Equity Loans
If you own a home, you might qualify for a home equity loan or line of credit. These loans use your home as collateral, potentially offering lower interest rates but adding risk if you cannot make payments.
How to Choose a Debt Consolidation Plan
Choosing the right debt consolidation plan requires careful consideration. Here are some steps to guide you:
- Assess Your Debt: List all your debts, including interest rates and monthly payments.
- Research Lenders: Compare interest rates, terms, and fees from multiple lenders.
- Check Your Credit Score: A higher credit score may qualify you for better rates.
- Consult a Financial Advisor: Seek professional advice to understand the impact on your financial health.
Potential Risks of Debt Consolidation
While debt consolidation offers many benefits, it's not without risks:
- Longer Repayment Periods: Some plans extend the repayment period, which might increase the total interest paid over time.
- Collateral Risk: Using your home as collateral can put your property at risk if payments are missed.
- Fees and Costs: Be aware of any hidden fees or costs associated with consolidating your debt.